Phillip Securities raised its price target on Palantir Technologies (NASDAQ: PLTR) from $215 to $248 on Monday, November 16, maintaining a “Buy” rating on strong third-quarter 2026 results.
As analyst Alif Fahmi said, revenue for the period met expectations, while profit after tax and minority interests (PATMI) exceeded forecasts, reaching 84% of Phillip Securities’ full-year 2026 estimates.
The brokerage accordingly raised its full-year 2026 revenue forecast by 5% and PATMI estimate by a further 9%, citing stronger-than-expected government and commercial sales, as well as improved management guidance.
Advertisement
Overall, Phillip Securities now expects Palantir to generate $8.53 billion in fiscal 2026 revenue, representing 91% year-over-year (YoY) growth, alongside adjusted operating income of $5.25 billion.
The new PLTR price target represents 48% upside from the last closing price of $167.99.
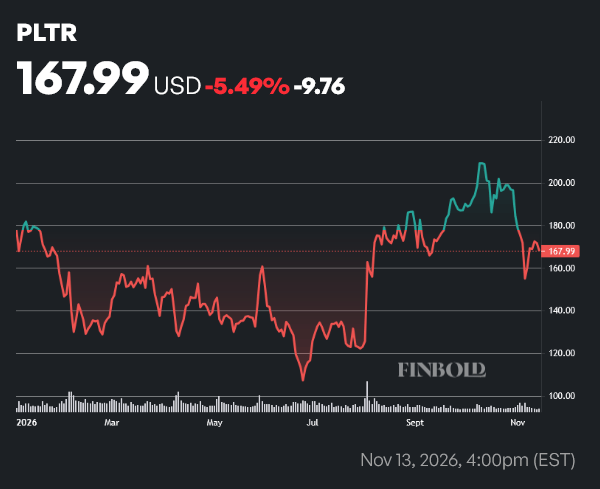
Palantir stock forecast raised on strong quarterly performance
Palantir’s growth continues to be driven by accelerating demand for its Artificial Intelligence Platform (AIP), improving pilot-to-production conversions, and strong momentum in the U.S. commercial business.
Notably, group revenue increased 92% year-over-year, supported by a 148% increase in U.S. commercial revenue. Now, Phillip Securities expects U.S. commercial revenue growth to remain above 143% year-over-year, supported by expanding enterprise artificial intelligence (AI) adoption.
Furthermore, Palantir’s operating performance also remains strong. For instance, its gross profit margin has reached 85% over the last 12 months. That said, Fahmi’s revised Palantir stock price target of $248 is based on a discounted cash flow (DCF) valuation model, and the analyst keeps his terminal growth assumptions unchanged.
Palantir valuation concerns remain, but Wall Street is optimistic
Despite the improved earnings outlook, however, the software company’s valuation remains a matter of debate. Namely, its market capitalization hovers around $405 billion, while its price-to-earnings (PE) ratio of 119 shows investors have high.
Advertisement
Nonetheless, Goldman Sachs, Bank of America (BofA), and Rosenblatt have also reiterated their “Buy” ratings, citing strong commercial momentum and growing opportunities in Sovereign AI. In fact, Rosenblatt highlighted a 138% year-over-year (YoY) increase in adjusted operating income and a 139% rise in free cash flow, which reached 52% of revenue.
Baird likewise maintained its “Outperform” rating, pointing to Palantir’s 13th consecutive quarter of accelerating revenue growth. At the same time, though, StoneX retained its “Hold” rating despite acknowledging the company’s strong quarterly performance.
Featured image via Shutterstock