Palo Alto (NASDAQ: PANW) stock climbed 4.5% on November 19 following strong fiscal first-quarter 2027 results and raised its full-year financial outlook.
For the quarter, the cybersecurity company reported adjusted earnings per share (EPS) of $1.05, beating analyst expectations of $0.97, while revenue came in at $3.45 billion, surpassing $3.31 billion forecasts.
Subscription and support revenue also rose 40% to $2.76 billion, while product revenue increased 37% to $595 million. At the same time, next-generation security annual recurring revenue reached $9.73 billion.
“We had a strong start to the year with a record Q1 and delivered one of our highest NGS ARR beats ever as our customers turn to us to protect them against an unprecedented threat environment,” Nikesh Arora, chairman and chief executive officer of Palo Alto, wrote in a press release.
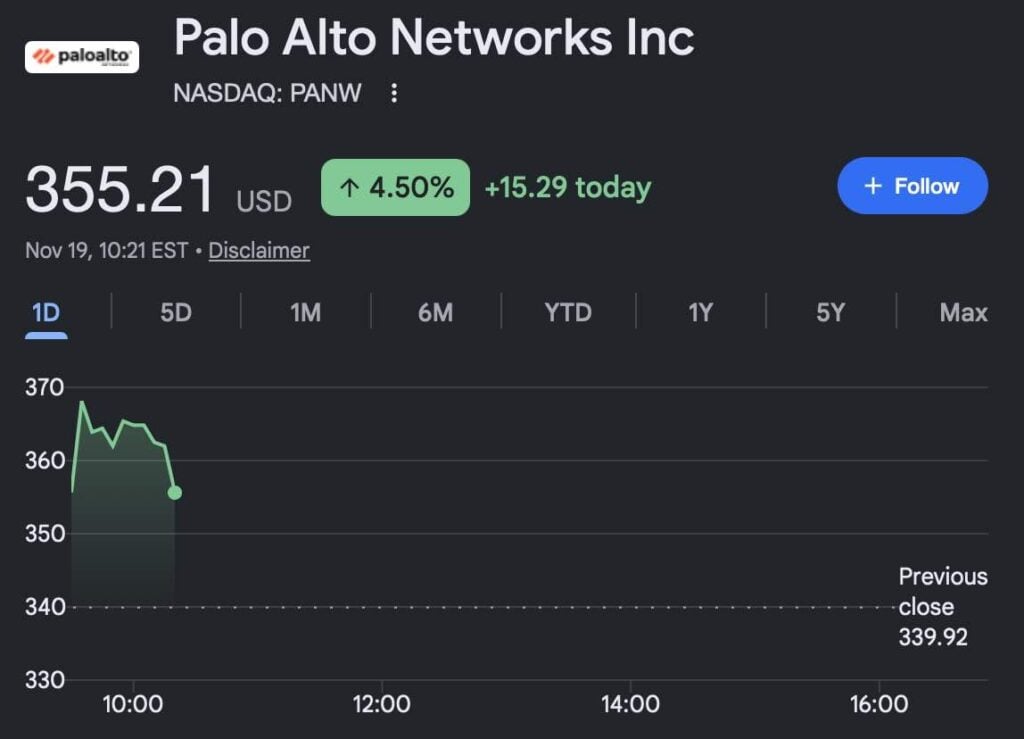
Palo Alto guidance raised
Following the strong quarterly performance, management raised its fiscal 2027 revenue guidance to between $14.52 billion and $14.57 billion, up from its previous forecast of $14.1 billion to $14.2 billion.
Adjusted earnings outlook was also increased to $4.26-$4.30 per share, exceeding the $4.18 analyst consensus. In addition, the company lifted its next-generation security annual recurring revenue target to $11.48-$11.54 billion.
“We delivered a very strong start to the year, in what is typically a seasonally slower Q1, fueled by acceleration across each of our segments. Given the current threat environment and demand we see ahead of us, we are materially raising our full year guidance,” Dipak Golechha, chief financial officer of Palo Alto, added.
Moreover, the company also announced it seeks to acquire Applied Compute, an AI startup worth, reportedly valued at $4.5 billion. According to the earnings report, the acquisition will allow Palo Alto “to deliver secure open weight models to our customers and accelerate the adoption of enterprise AI.”
Palo Alto stock price target raised
Wall Street analysts responded positively to the results. For instance, Morgan Stanley maintained its “Overweight” rating, arguing that Palo Alto’s first-quarter performance demonstrates rising enterprise demand.
Susquehanna also reiterated its “Positive” rating and $425 PANW price target. The firm said the latest results exceeded expectations, driven by the continued development of its platform strategy and growing demand for security products.
Similarly, Wedbush maintained its “Outperform” rating and $400 price forecast, while keeping the stock on its list of Top Investment Picks. The financial services company also highlighted Palo Alto’s ability to capitalize on rising demand for AI-powered cybersecurity solutions, adding that it supports the higher fiscal 2027 guidance.
Featured image via Shutterstock