JPMorgan reiterated its Overweight rating and $1,540 price target on Micron (NASDASQ: MU) stock on September 28, two days ahead of the company’s earnings report.
The bank cited stronger-than-expected pricing momentum and continued tightness across the memory market. Specifically, analyst Arlan Sur expects Micron to report August-quarter revenue, gross margin, and earnings per share above consensus estimates of $51.4 billion, 86.2% and $31.73, respectively.
Furthermore, Sur said pricing momentum remained strong throughout the quarter despite earlier comments from management that the pace of price increases could moderate. This, he argued, could reflect Micron’s efforts to preserve customer relationships and secure longer-term supply and capacity agreements than a deterioration in demand.
“MU is set to report Aug-Qtr (F4Q26) earnings on Wednesday (Sept 30), and we see the setup as constructive with multiple beat-and- raise levers still in play against a memory backdrop that remains structurally tight across both DRAM and NAND,” Sur wrote.
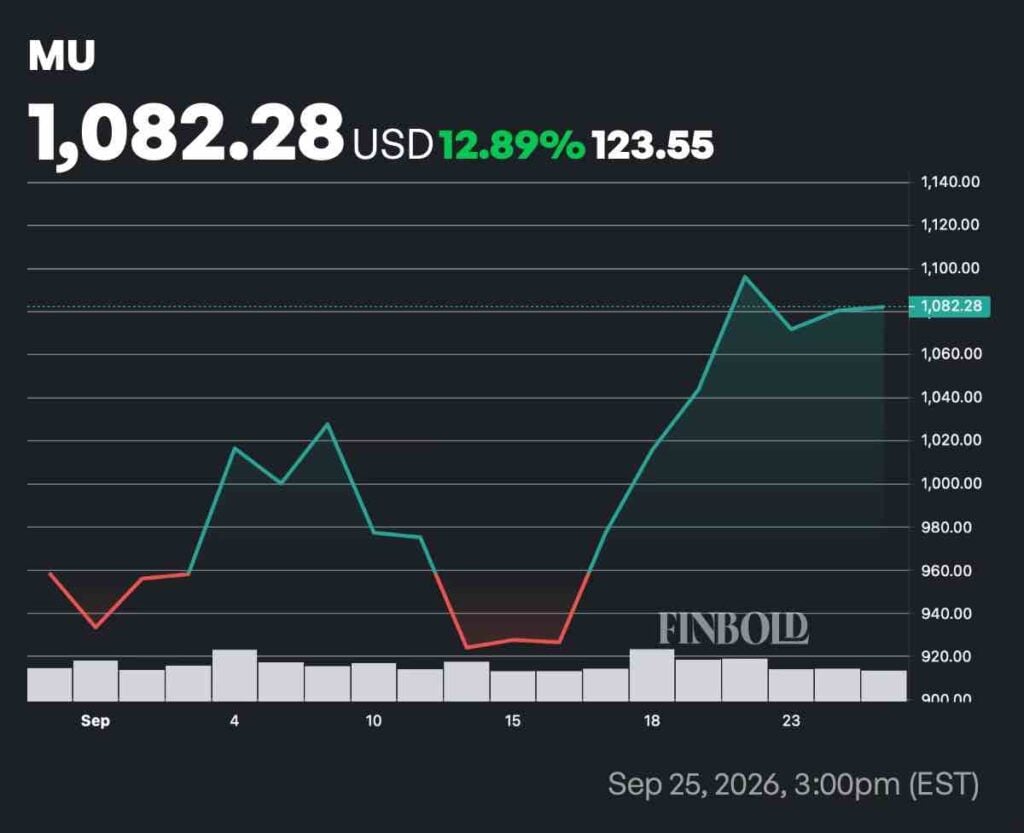
Micron shares are currently trading at around $1,082.28, giving the company a market capitalization of approximately $1.22 trillion. The stock has gained 12.89% over the past year.
JPMorgan also expects Micron to raise its guidance for the November quarter, pointing to stronger aggregate demand signals from customers, management’s expectation that 2027 will be tighter than 2026, and continued momentum in the company’s HBM4 ramp, which has already seen more than $1 billion worth of HBM4 shipped as of the May quarter.
Agentic AI demand will push Micron higher, Baird says
Meanwhile, Baird raised its Micron stock price target from $1,280 to $1,520 while maintaining an Underperform rating. The firm identified several factors behind the higher target, most notably stronger agentic AI demand, which has been driving CPU requirements.
In addition, the wealth management company noted slower industrywide DRAM supply-bit growth expected in 2027 and a higher-margin profile for HBM next year. Namely, Baird expects industrywide AI CPU unit growth of about 40% in 2027 and has raised its DRAM pricing assumptions for the second half of 2026.
At the same time, it now forecasts total DRAM bit growth of more than 30% in 2026, slowing to around 20% in 2027, including HBM. More specifically, HBM bit demand is expected to grow by roughly 60% year over year.
The firm also expects acute memory shortages to persist into 2027, while server unit growth could accelerate from 18-19% in 2026 to 20-22% in 2027.
Image source: lentamart/Shutterstock.com