Nvidia’s (NASDAQ: NVDA) dominance of the artificial intelligence (AI) chip market faces growing challenges amid leadership uncertainty.
While the chipmaker remains central to the AI boom, these setbacks could create opportunities for rivals as investors look beyond the industry’s biggest player for growth in 2027.
The pressure is increasingly visible in Nvidia’s stock performance. On November 20, shares fell another 3%, putting the company on track for its seventh consecutive weekly decline, its longest losing streak since 2008.
The sell-off also pushed Nvidia below Alphabet (NASDAQ: GOOGL) in market capitalization, making it the fourth-most valuable U.S. company.
As of press time, NVDA shares were valued at $125.53, down 14% at Friday’s market close.
The decline came despite Nvidia’s first earnings report since co-founder Jensen Huang’s resignation, which failed to ease concerns about the leadership transition and the sustainability of AI spending.
A November 14 report by J.P. Morgan Asset Management also highlighted growing competitive pressure as major AI developers diversify accelerator suppliers and develop custom chips.
The report estimated that Nvidia accounted for 28% of announced frontier AI laboratory computing agreements, compared with 23% for Broadcom’s custom chips and 18% for AMD’s graphics processing units (GPUs). This marks a notable shift from Nvidia’s estimated 80% to 90% share of AI chip revenue in 2024 and 2025.
Although these figures measure different metrics and do not indicate an equivalent decline in overall market share, they highlight growing competition for future AI infrastructure spending.
Against this backdrop, two semiconductor stocks could offer investors alternative exposure to the AI boom and potentially outperform Nvidia in 2027.
Advanced Micro Devices (NASDAQ: AMD)
Advanced Micro Devices (NASDAQ: AMD) is one of Nvidia’s most direct competitors as demand for alternative AI accelerators increases.
The company’s latest financial outlook provides a strong foundation for the bullish case. On November 3, AMD forecast that its revenue would increase by more than 80% in 2027, exceeding analysts’ expectations of approximately 77% growth, according to Reuters.
CEO Lisa Su also projected that data-center chips would account for approximately 80% of the company’s revenue next year and drive most of its revenue and earnings growth.
AMD’s data-center business is already gaining momentum, with the third-quarter revenue from the segment jumping 97% year over year to a record $8.55 billion, exceeding analysts’ expectations of $8.20 billion.
The company is also expanding beyond individual processors to compete with Nvidia’s integrated AI computing systems. Its Helios rack-scale platform, which combines the MI455X accelerator with its latest server processors, is expected to support its broader push into AI infrastructure.
While Nvidia is preparing its next-generation Rubin platform for 2027, AMD’s expanding customer relationships and improving AI infrastructure offerings could help it capture a larger share of future spending.
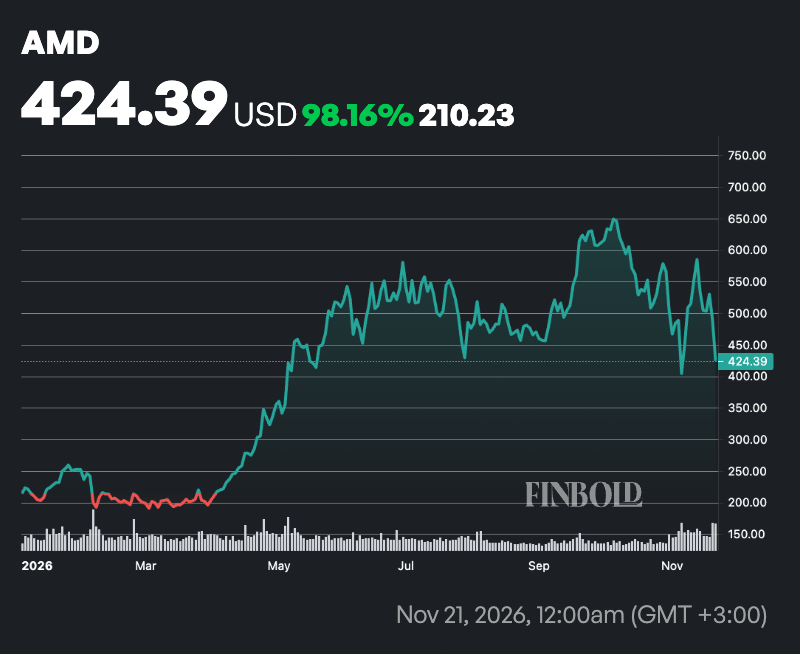
By press time, AMD stock was trading at $424.39, down 13% at last market close but remains 90% up in 2026.
Micron Technology (NASDAQ: MU)
Micron Technology (NASDAQ: MU) offers a different route to benefiting from the AI infrastructure boom, with its growth prospects tied to increasing demand for high-bandwidth memory (HBM).
Unlike AMD, which directly challenges Nvidia in AI processing, Micron supplies memory components that help power advanced AI accelerators. These components are increasingly important as AI models become more complex and require greater computing capacity.
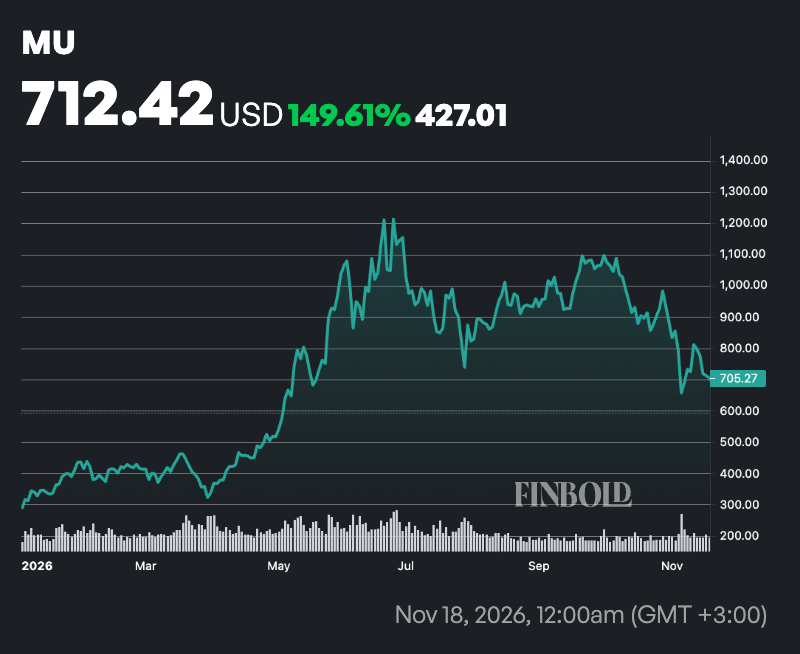
Indeed, this position has pushed MU to emerge among the best-performing stocks in recent months. As of press time, MU shares were valued at $594.51, down 13% at last market close but up 150% YTD.
The company’s latest earnings commentary highlights the strength of this demand. According to its fiscal fourth-quarter 2026 earnings call, Micron completed agreements covering the vast majority of its calendar 2027 HBM supply, with significant year-over-year price increases. The company also reported continued progress in ramping up its next-generation HBM4 products.
This provides greater revenue visibility heading into 2027, particularly as semiconductor manufacturers and cloud computing companies expand their AI infrastructure.
Micron is also benefiting from growing demand for data-center storage. During its fiscal fourth quarter, data-center SSD revenue approached $10 billion, more than ten times the level recorded a year earlier, according to management’s earnings commentary.
The development suggests that AI infrastructure spending is creating opportunities beyond GPUs, extending into memory and storage components required to train and operate increasingly sophisticated models.
However, Micron’s exposure to the memory market also presents risks. The industry is cyclical, and increased production capacity could eventually put pressure on memory prices and profit margins.
Nevertheless, continued HBM demand, contracted supply, and its expanding data-center business could provide important growth drivers in 2027.
Featured image via Shutterstock