Nvidia (NASDAQ: NVDA) stock could rebound towards $175 following the company’s earnings announcement on Tuesday, November 17, according to a forecast by ChatGPT.
However, the artificial intelligence model assigned a 30% probability to a decline to $140–$150 if the chipmaker disappoints with its forward guidance or fails to reassure investors about its leadership transition.
The forecast outlines three possible outcomes following Nvidia’s fiscal third-quarter 2027 results. The base case points to a recovery towards $170–$180 by November 20, while the bullish scenario projects $185–$200. Conversely, the bearish outlook anticipates a decline of up to 14.1%.
Advertisement
At press time, Nvidia shares were trading at $162.85 after several consecutive sessions of losses amid controversy surrounding Jensen Huang’s departure.
ChatGPT assigned the base case the highest probability, at 50%, assuming Nvidia delivers results broadly in line with Wall Street expectations.
Under this scenario, shares could reach $170–$175 by November 20 before consolidating within the $170–$180 range through December 4. A sustained recovery could take NVDA towards $180–$190 by January 2027.
Nvidia revenue assumptions
This outcome assumes quarterly revenue of $109 billion to $111 billion, EPS of $2.47–$2.55, and data center revenue above $100 billion, alongside solid fourth-quarter guidance.
The bullish scenario carries a 20% probability and assumes a stronger earnings beat and upbeat guidance. Shares could climb to $185–$195 between November 18 and November 20, approach $200 by December 4, and potentially reach $205–$220 by January 2027.
This would require revenue exceeding $112 billion, EPS above $2.55, and data center sales topping $103 billion, supported by sustained Blackwell demand and accelerating adoption of Nvidia’s next-generation Vera Rubin platform.
Advertisement
Meanwhile, the bearish scenario carries a 30% probability, with shares potentially falling to $140–$150 between November 18 and November 20. This would represent a 7.9%–14.1% decline from the reference price.
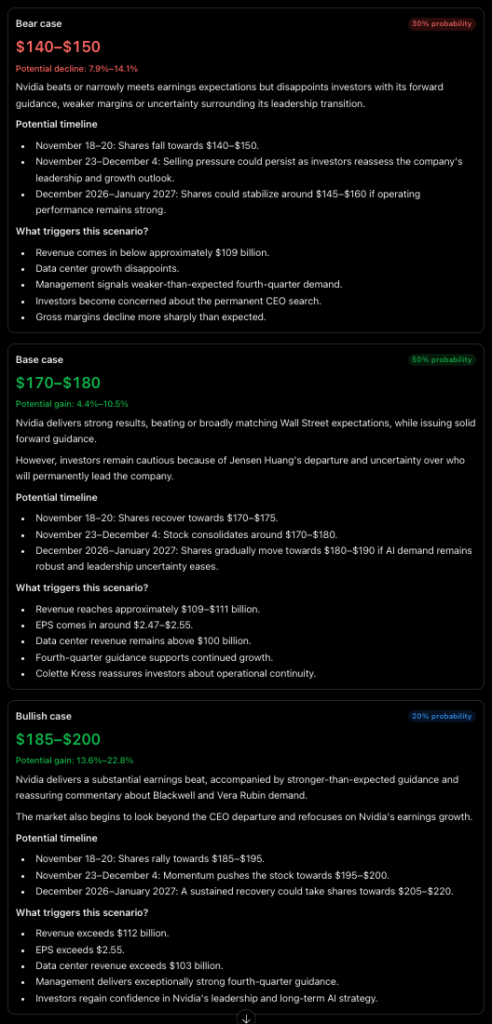
Revenue below $107 billion, EPS under $2.40, and weaker-than-expected guidance could trigger further selling, alongside deteriorating gross margins and concerns about AI infrastructure spending. Shares could subsequently stabilize between $145 and $160 through January 2027.
Nvidia earnings expectations
Wall Street expects Nvidia to report approximately $109.3 billion in fiscal third-quarter 2027 revenue. Consensus EPS stands at $2.47, representing approximately 90% year-over-year growth. Revenue estimates range from $100.48 billion to $116.25 billion, while EPS projections span $2.26 to $2.70.
Data center revenue is expected to reach approximately $101.8 billion, driven by demand for Blackwell graphics processing units (GPUs) as cloud providers expand their AI infrastructure. Investors will also watch for adoption signals surrounding Vera Rubin.
Gross margins will be another key metric. Nvidia previously guided for a non-GAAP gross margin of approximately 74%, plus or minus 0.5 percentage points, compared with 75% in the second quarter. Higher production and memory costs could put additional pressure on profitability.
Nvidia leadership transition adds uncertainty
Huang’s departure as CEO and a board member adds another risk ahead of the announcement. CFO Colette Kress has been appointed interim CEO while Nvidia searches for a permanent successor.
Advertisement
Huang has played a central role in the company’s product strategy, AI partnerships, and customer relationships.
Consequently, investors will look for reassurance about operational continuity and Nvidia’s long-term direction.
Featured image via Shutterstock