Intel (NASDAQ: INTC) could have another catalyst to reclaim the $100 level as rising demand for artificial intelligence (AI) infrastructure supports its server processor business, according to RBC Capital.
The investment bank reiterated its ‘Sector Perform’ rating on the semiconductor giant, maintaining a $100 price target.
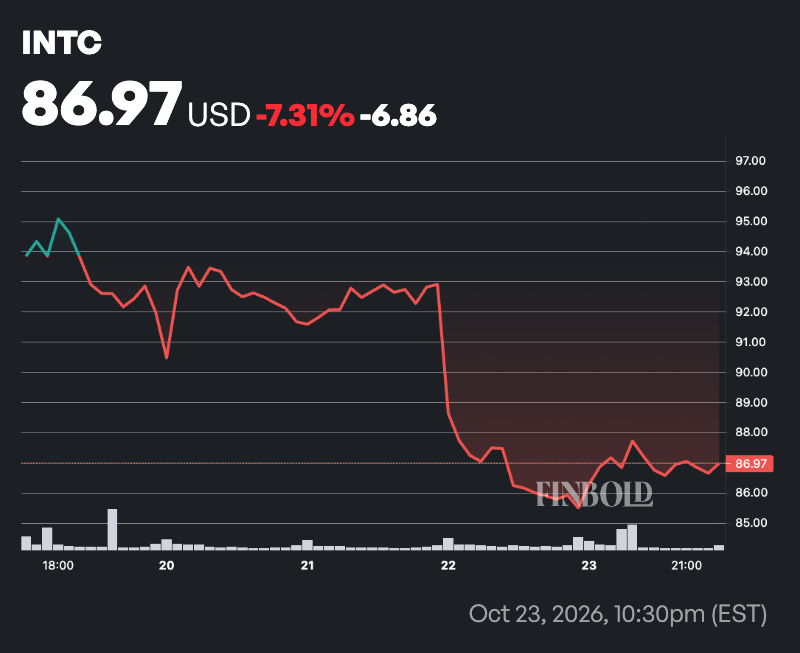
As of press time, Intel shares were trading at $86.96, leaving the price target approximately 15% above that level.
RBC expects Intel to deliver another earnings beat and raise its outlook, supported by robust demand for agentic AI, which refers to AI systems capable of carrying out tasks with limited human intervention.
Impact on Intel revenue
The firm anticipates that this demand will support at least a 5% revenue beat and a 3% to 5% increase in guidance. Double-digit growth in server CPU volumes is also expected to continue into 2027, with a favorable product mix and average selling prices potentially providing additional support.
The server CPU opportunity is particularly important as AI infrastructure spending expands beyond graphics processing units (GPUs). CPUs remain essential for coordinating workloads, managing data and supporting the broader computing infrastructure used to operate AI systems.
Despite the positive outlook for server processors, supply availability remains a key uncertainty. RBC also highlighted weak PC demand as an overhang, reflecting the risk that softness in Intel’s traditional computing business could offset gains elsewhere.
Improved Panther Lake CPU availability could boost yields on Intel’s 18A process, while advances in foundry operations and packaging could strengthen its competitive position. RBC expects EMIB-T advanced packaging to generate $3 billion to $5 billion in 2028.
Wall Street is mainly bullish on INTC stock
Meanwhile, broader analyst sentiment toward INTC shares is more positive. According to TradingView forecasts, the average one-year price target stands at $119.85, implying approximately 37.82% upside from the stock’s current price.
The forecast range extends from $80 to $200, highlighting the substantial uncertainty surrounding Intel’s longer-term prospects.
The analyst-rating distribution leans toward a ‘Buy’ consensus, with 14 ‘Strong Buy’ ratings, five ‘Buy’ ratings, 32 ‘Hold’ ratings, and one’ Strong Sell’ rating among 52 analysts.
Intel is scheduled to report third-quarter results on October 29, with investors watching for stronger AI-driven revenue and easing supply constraints.
The company reported second-quarter revenue of $16.1 billion, up 25% year over year, while Data Center and AI revenue surged 59% to $6.3 billion, supporting RBC’s growth outlook.
However, Intel raised its 2026 capital expenditure forecast to $20 billion from $18 billion to meet AI demand, increasing investment costs. Its foundry business also faces challenges, with just $293 million of its $5.8 billion in second-quarter revenue coming from external customers.
Featured image via Shutterstock