HSBC raised its price target on Tesla (NASDAQ: TSLA) to $157 from $125 while maintaining a “Reduce” rating on the stock.
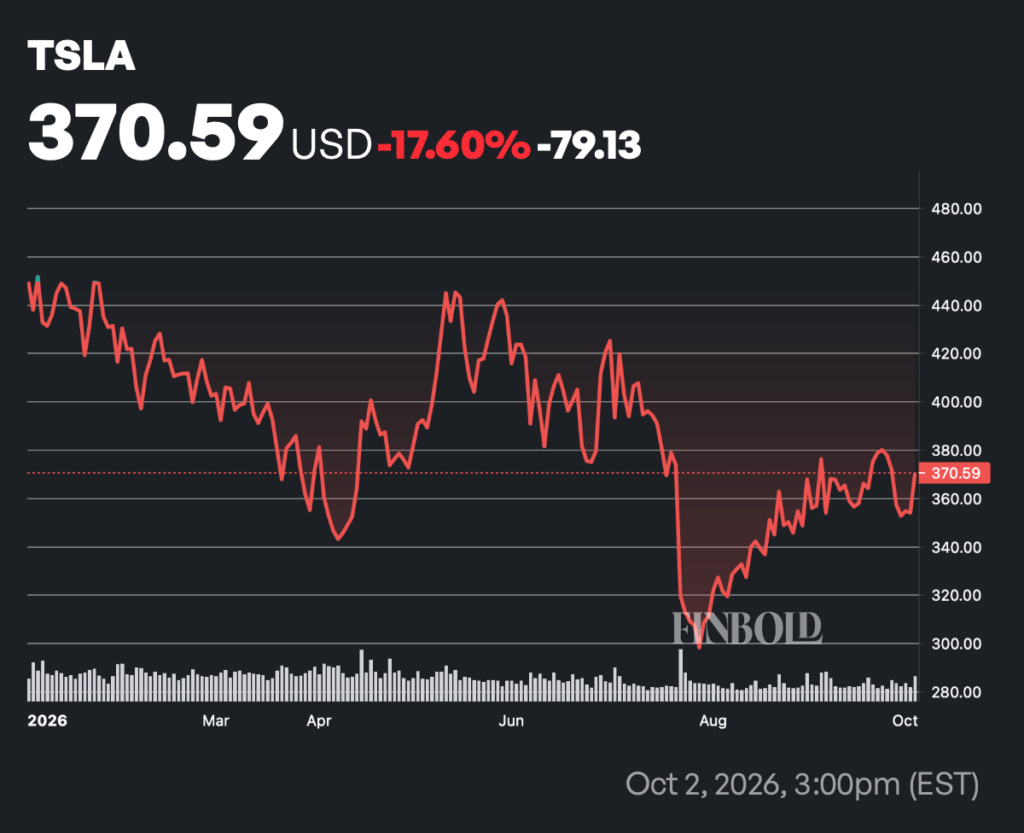
Tesla shares closed at approximately $370 on October 2, more than 135% above HSBC’s revised target and down about 17% year-to-date (YTD) despite a notable 4.7% gain on October 2 that resulted from better-than-expected third-quarter deliveries.
Notably, Tesla delivered 486,532 vehicles in the third quarter, more or less 7% above market estimates. The company’s deliveries also exceeded expectations cited by HSBC itself, although they declined 2% year over year, which the bank attributed the annual decline to pull-forward effects related to the expiration of IRA tax credits.
Production, however, remained a point of weakness. Specifically, Tesla produced 464,391 vehicles during the quarter, below both its deliveries and the 486,761 consensus estimate. Production was also 3.7% below HSBC’s forecast.
Tesla’s energy business similarly underperformed expectations. Notably, energy storage deployments reached 13.7 gigawatt-hours in the third quarter, 19% below consensus and 24% below HSBC’s estimate.
At the same time, deployments increased 11% year over year through the first three quarters of 2026, well below HSBC’s initial forecast for 40% growth. The bank subsequently lowered its full-year deployment forecast but still expects 35% year-over-year growth in the fourth quarter.
Tesla stock price target raised; price remains volatile
Tesla’s stock performance has been volatile throughout 2026. The shares ended 2025 at $450 before falling to $372 by the end of March, where they remain at the time of writing after months of constant ups and downs.
Despite the wide gap between HSBC’s target and Tesla’s market price, Wall Street’s overall view is considerably more bullish. Analysts tracked by TipRanks have given the carmaker 12 “Buy” ratings, 11 “Holds,” and two “Sells”, and the same data gives the mean Tesla stock price target of $391 for the next twelve months.
The valuation appears driven, in part, by Tesla’s growing order backlog and the expansion of its robotaxi service, which has begun expanding unsupervised operations across Texas and Florida.
At the same time, though, Tesla’s valuation remains a key concern for more cautious analysts, with Tesla trading at a price-to-earnings (P/E) ratio of 345. HSBC’s $157 target therefore reflects a much more conservative view of Tesla’s valuation and the pace at which its automotive, energy, and autonomous-driving businesses can translate into earnings growth.
Featured image via Shutterstock