Even after Intel’s (NASDAQ: INTC) massive run in 2026, one Wall Street analyst argues the stock remains undervalued.
In this vein, Melius on September 16 reaffirmed its ‘Buy’ rating and maintained a $165 price target on the semiconductor giant. The target implies nearly 70% upside from Intel’s current price of about $97.
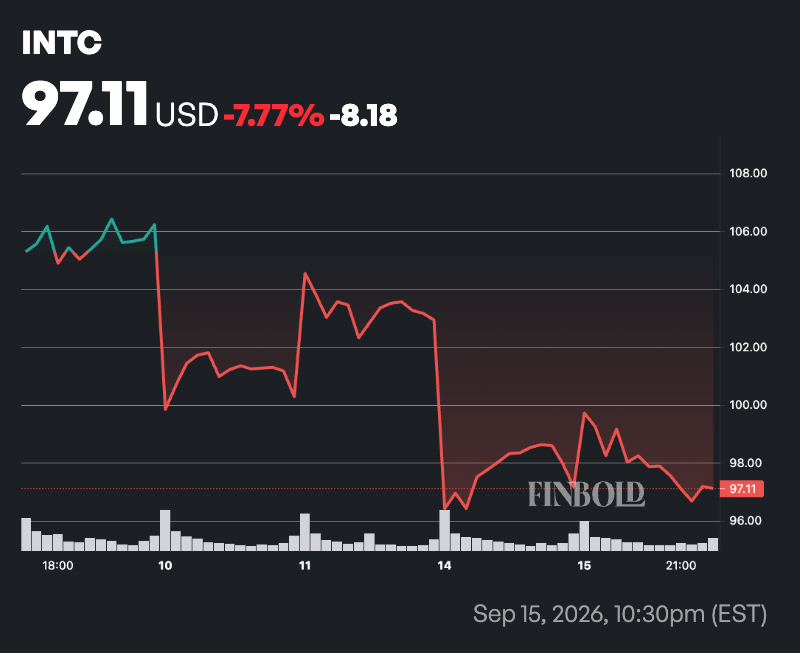
The stock remains well above its 52-week low, although it has retreated from highs near $140 reached earlier this year amid broader semiconductor weakness and concerns over AI spending growth.
According to Melius analyst Ben Reitzes, Intel’s improving execution, pricing power, and foundry progress support a multi-year growth story.
INTC’s stock path to $200
Reitzes argued that Intel’s foundry division and product business could each be worth more than $80 per share, underpinning a sum-of-the-parts valuation that places fair value near $200 per share.
The analyst highlighted several catalysts supporting the bullish outlook, including stronger near-term financial performance, progress under CEO Lip-Bu Tan, and continued advancement of Intel’s manufacturing roadmap.
Reitzes also noted that Intel’s 2027 capital expenditure plans could exceed 2026 spending by more than $20 billion as the company accelerates foundry investments.
Melius further pointed to Intel’s recent disclosure that its 18A manufacturing process has entered risk production, while its upcoming 14A node continues to attract customer interest.
Investor attention remains focused on Intel’s foundry business as the company seeks to challenge TSMC in advanced chip manufacturing.
Recent reports indicate SK Hynix is exploring a potential arrangement with Intel that could involve memory-chip production at Intel’s Ohio campus.
While discussions remain preliminary and no agreement has been finalized, the development is viewed as a potential source of external demand for Intel’s manufacturing capacity.
Intel’s turnaround rewards
Intel has also continued expanding its customer base. The technology company has disclosed relationships with customers including Microsoft, Tesla, Broadcom, and Fortinet, while industry reports have linked its manufacturing and packaging operations to additional technology firms.
The analyst noted that Intel sold approximately $20 billion worth of stock at around $95 per share earlier this year, helping fund its foundry ambitions while resulting in roughly 3.5% shareholder dilution.
At the same time, Intel’s latest quarterly results reinforced investor confidence in the turnaround strategy.
The company reported second-quarter revenue of $16.1 billion, up 25% year-over-year, while adjusted earnings of $0.42 per share exceeded Wall Street expectations.
Management also raised capital expenditure plans and issued third-quarter guidance above analyst forecasts.
Featured image via Shutterstock.