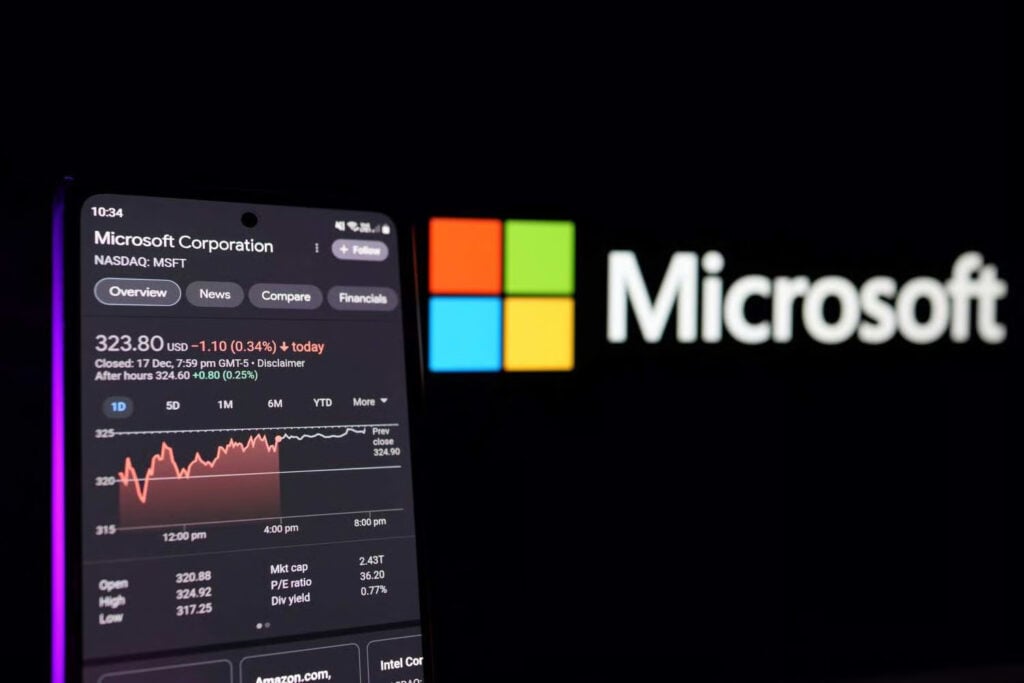
Oppenheimer has raised its Microsoft (NASDAQ: MSFT) stock price target to $570 from $515 while reiterating its ‘Outperform’ rating.
In an investor note on September 22, the firm backed its bullish outlook, citing accelerating growth across Azure, Microsoft 365, and the company’s expanding artificial intelligence business. The new target implies roughly 13.6% upside from Microsoft’s recent price of $501.61.
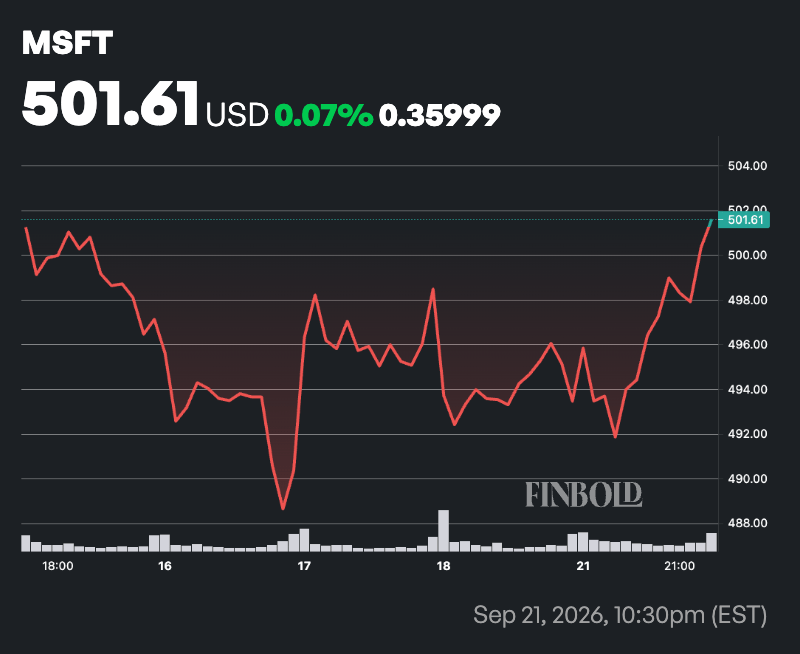
The price target increase follows a recent headquarters meeting with Microsoft management, after which Oppenheimer said its thesis of accelerating growth combined with capital discipline remains intact.
The firm expects Azure cloud services and Microsoft 365 Commercial to sustain business acceleration throughout fiscal 2027, supported by growing Copilot adoption and additional AI computing capacity coming online.
According to the analyst, Copilot monetization remains strong as enterprises increasingly standardize on Microsoft as their primary AI platform.
Oppenheimer also highlighted improving efficiency and capital allocation, which it believes should lead to more predictable capital expenditures and positive free cash flow generation. The firm noted that additional compute capacity should help support future demand from enterprise customers.
Wall Street bullish on MSFT stock
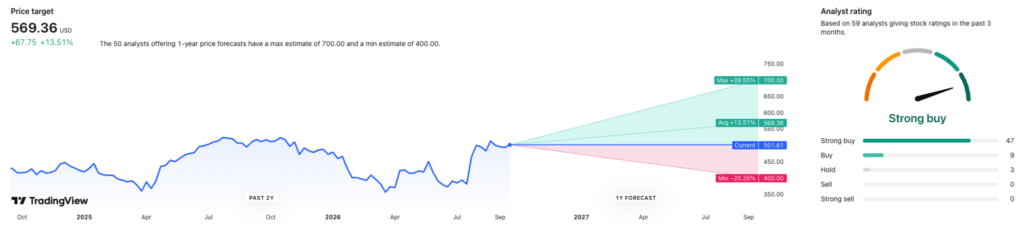
The latest target places Oppenheimer near the broader Wall Street consensus. Analyst forecasts show an average 12-month Microsoft price target of about $569, with estimates ranging from $400 to $700.
The stock currently carries a ‘Strong Buy’ consensus rating from analysts. The average target suggests about 13.5% upside from current levels.
Microsoft’s investment case remains driven by its AI and cloud businesses. The company reported Azure revenue growth of 43% in fiscal fourth quarter 2026 and guided for 45% growth in the first quarter of fiscal 2027, marking the cloud platform’s fastest expansion in several years.
The technology giant has also seen rapid adoption of Microsoft 365 Copilot, with paid seats surpassing 30 million.
While maintaining a positive outlook, Oppenheimer flagged several risks, including slower Azure and Microsoft 365 growth if enterprise AI spending is pulled forward, as well as potential cloud margin pressure and lower capital expenditure efficiency. The concerns mirror broader Wall Street debates over the sustainability of heavy AI infrastructure spending.
Despite these risks, analyst sentiment remains bullish, with firms such as Bank of America and Morgan Stanley maintaining price targets near $600, supported by Azure’s accelerating growth, expanding Copilot adoption, and Microsoft’s growing AI ecosystem.
Featured image via Shutterstock