Wall Street analysts have updated their price targets for Nvidia (NASDAQ: NVDA) following the chipmaker’s November 17 earnings report.
The revisions followed a strong third-quarter performance, with Nvidia beating revenue and earnings expectations and issuing fourth-quarter guidance above Wall Street estimates.
Nvidia reported fiscal third-quarter revenue of $115.8 billion, up 103% year over year and above analyst expectations of approximately $108.85 billion. Adjusted earnings per share reached $2.68, compared with the $2.47 consensus estimate.
Data Center revenue, which accounts for most of Nvidia’s business, increased 110% to $107.6 billion as demand for AI computing infrastructure continued to drive growth.
The technology company forecast fourth-quarter revenue of approximately $130 billion, plus or minus 3%, exceeding Wall Street’s expectations of roughly $125 billion. Management also indicated that fiscal 2028 revenue growth could reach approximately 75%.
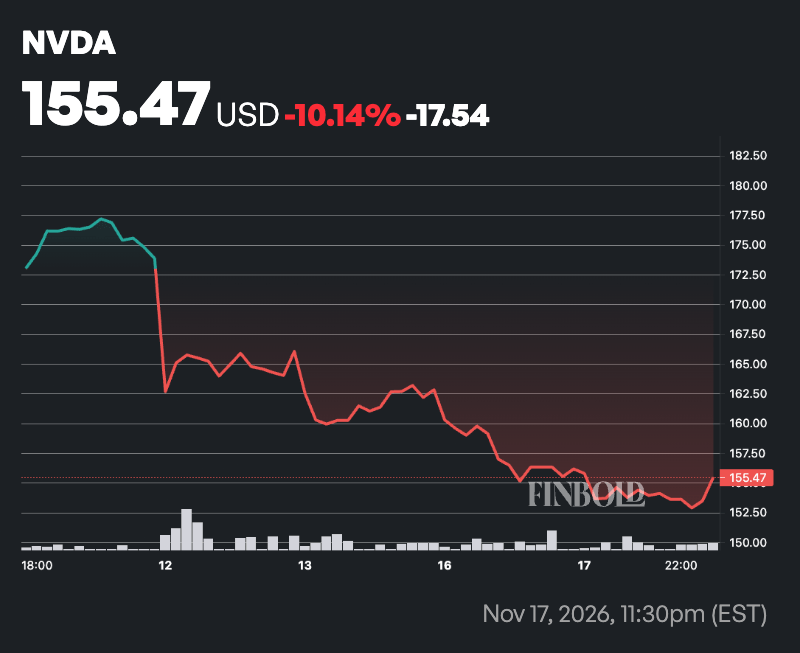
Nvidia shares initially rose 4.57% in after-hours trading to $162.56 after closing the November 17 session at $155.46, down approximately 0.48%. In premarket trading on Wednesday, NVDA shares gained another 3.35% to $160.
Analysts take on Nvidia stock
Among the analysts, Goldman Sachs’ James Schneider reiterated a ‘Buy’ rating and maintained his $220 price target. He expects the shares to trade modestly higher following the strong results and above-consensus guidance. However, he identified CEO succession, organizational planning, visibility into AI data-center infrastructure deployments through 2028, and the financial health of Nvidia’s customers as key factors influencing the stock’s performance. Goldman also noted that investor positioning remained neutral to negative, potentially leaving room for further gains if management addresses these concerns.
Citi analyst Atif Malik maintained a ‘Buy’ rating and a $225 price target while raising his earnings estimates, reflecting stronger expectations following the results and improved long-term revenue outlook.
Barclays also maintained its bullish stance, reiterating an ‘Overweight’ rating and a $210 price target, supported by Nvidia’s growth prospects and continued AI infrastructure demand.
Cantor Fitzgerald reiterated its bullish rating and $250 price target while raising its calendar 2027 earnings-per-share estimate to $17, above the analyst consensus of $15.64.
Bearish analysts on NVDA shares
Despite the earnings beat, several investment banks lowered their price targets, reflecting more conservative valuation assumptions.
Jefferies cut its Nvidia price target to $250 from $300 while maintaining a ‘Buy’ rating, despite continued confidence in AI infrastructure spending and demand for Nvidia’s computing products.
Wells Fargo similarly reduced its target to $250 from $300 while retaining its bullish recommendation, adopting a more cautious valuation outlook despite Nvidia’s stronger results and guidance.
Piper Sandler analyst Harsh Kumar lowered his price target to $230 from $300 while maintaining an ‘Overweight’ rating, implying approximately 48% upside from the reference price of $155.46. However, the firm raised its fiscal 2027 and 2028 earnings-per-share estimates by 5% and 9%, respectively. The lower target reflects a reduced valuation multiple rather than weaker earnings expectations. Piper considers Nvidia attractively valued for longer-term investors but expects the shares to remain range-bound until greater clarity emerges around the company’s leadership transition.
Morgan Stanley analyst Joseph Moore also lowered his price target to $260 from $267 while maintaining an ‘Overweight’ rating, making a relatively modest adjustment to the firm’s valuation outlook.
Overall, Wall Street’s initial response to Nvidia’s earnings remains broadly positive, with most analysts maintaining bullish ratings despite some price-target reductions.
However, the leadership transition following Jensen Huang’s departure as CEO remains an important consideration, alongside questions about Nvidia’s valuation and the sustainability of its growth.
Featured image via Shutterstock