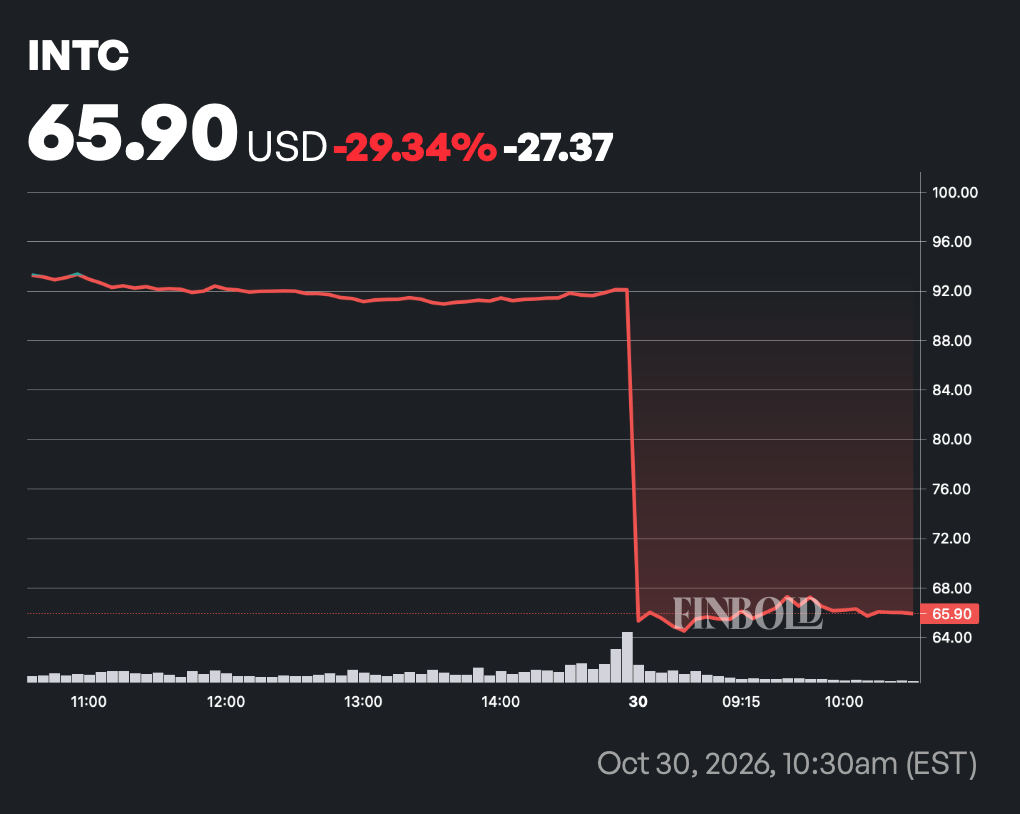
Intel (NASDAQ: INTC) stock is down 29% on October 30, trading at $65.9 at the time of publication, following a wave of price target cuts and downgrades from Wall Street analysts in the wake of the chipmaker’s third-quarter earnings report.
Among the most significant revisions, Roth Capital analyst Suji Desilva slashed his Intel price target by 41.67%, from $120 to $70, saying that while data center growth might be positive, manufacturing constraints could limit further upside.
Desilva also downgraded the stock to “Neutral” from “Buy,” citing weaker guidance that reflected headwinds in the client computing segment, demand adjustments, and the impact of a manufacturing accident.
Advertisement
The call echoed numerous other research notes that swept the market like a flood, with a total of 17 analysts slashing their forecasts in a day.

Wall Street turns bearish on Intel stock
Other revisions were likewise notable. Baird lowered its price target on Intel by 33.6% to $83 from $125 while maintaining a “Neutral” rating. The firm cited weaker revenue substitution between Intel’s client and server businesses.
While client revenue is expected to decline year-over-year (YOY) in the fourth quarter, Baird said, server revenue growth remains constrained by supply shortages involving wafers and substrates. Accordingly, the firm does not anticipate meaningful relief from these constraints until the second half of 2027
StoneX similarly retained its “Buy” rating but reduced its price target by 28.57%, from $140 to $100. In particular, the firm questioned Intel’s ability to expand supply quickly enough to meet its strategic objectives.
PC demand weakness might be Intel’s worst problem
Further, Jefferies analyst Blayne Curtis lowered his price target by 29.17%, from $120 to $85, while maintaining a “Hold” rating. Curtis characterized the December-quarter outlook as a “substantial” reset, pointing to lower client revenue and gross margins as PC customers reduced near-term demand.
Bank of America analyst Vivek Arya also downgraded Intel to “Neutral”, cutting his price target by 31.03%, from $145 to $100 due to weakness in the PC market and supply constraints. Arya also highlighted Intel’s limited progress in attracting external foundry customers, arguing that the company “has not communicated enough traction with external foundry customers.”
Advertisement
The broader analyst response thus suggests that Intel’s challenge extends beyond its latest quarterly performance. While data center demand and foundry expansion offer potential avenues for growth, weakening PC demand in particular has raised doubts about the pace of the company’s turnaround.
Featured image via Shutterstock