Nvidia (NASDAQ: NVDA) could be poised for another leg higher after breaking above a key technical resistance level, according to market analyst Ali Martinez.
In an X post on October 6, Martinez noted that NVDA shares are breaking out of a multi-month consolidation pattern that had capped gains for much of the second half of 2026.
The analyst identified the $238 area as a critical resistance zone. With the stock now trading at $239, Martinez projected a move toward approximately $280, implying upside of about 19% from the breakout point.
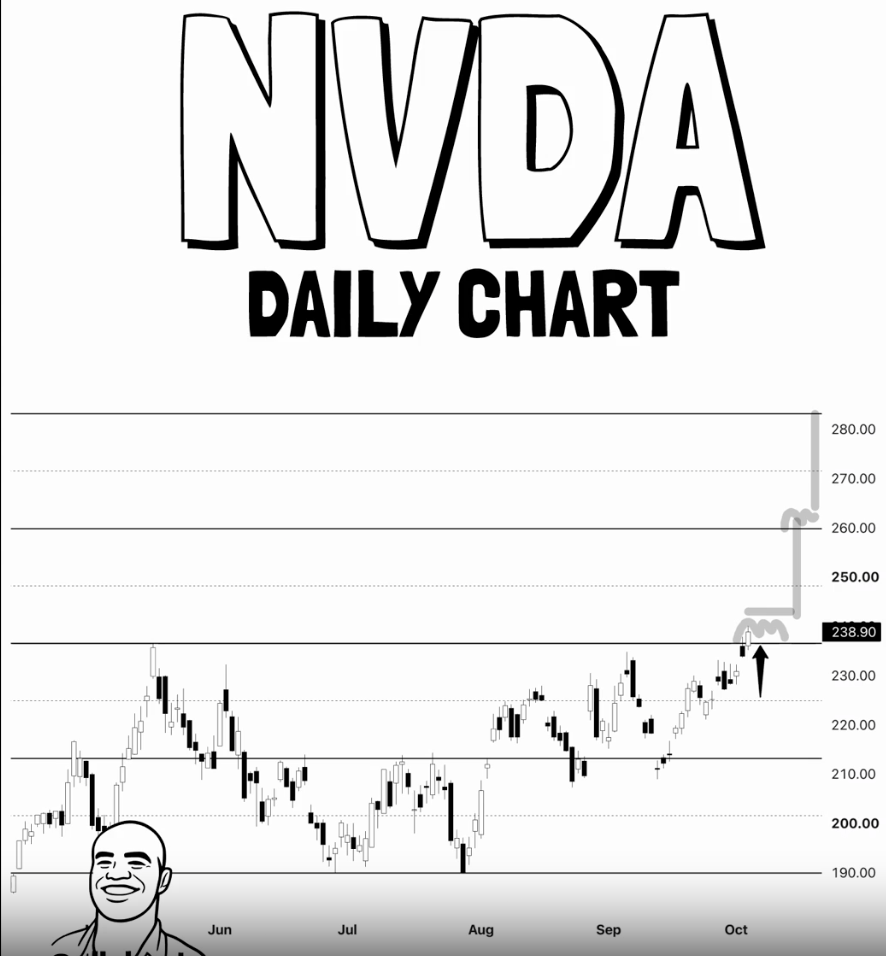
The setup suggests Nvidia may be entering a new bullish phase, with the former resistance zone potentially turning into support.
Nvidia stock backed by fundamentals
The technical breakout comes as Nvidia continues to benefit from strong demand for artificial intelligence infrastructure.
Much of the optimism stems from the technology company’s August earnings report, which reinforced its dominance in the AI sector.
For the second quarter of fiscal 2027, reported in August, Nvidia posted revenue of $96.2 billion, up 106% year-over-year and 18% sequentially, beating Wall Street expectations by about 4%.
Data Center revenue, Nvidia’s main growth driver, surged 117% year-over-year to $89 billion, accounting for about 92% of total sales, driven by continued AI infrastructure spending from hyperscalers, enterprises, and AI cloud providers.
The company reported GAAP earnings per share of $2.46, maintained a 75% gross margin, and generated approximately $21.3 billion in quarterly free cash flow.
Management said AI has reached an inflection point, with computing power increasingly translating into revenue-generating applications, while Blackwell Ultra and Vera Rubin are expected to support future growth.
At the same time, the semiconductor giant forecast third-quarter revenue of about $108 billion, above Wall Street estimates, despite assuming no Data Center compute revenue from China. It also projected roughly 70% revenue growth for fiscal 2028, well ahead of pre-earnings expectations.
NVDA buyback plan
Adding to the bullish sentiment, Nvidia expanded its share repurchase authorization by a record $150 billion in September, raising total remaining buyback capacity to about $235 billion through fiscal 2028. The move was widely viewed as a strong signal of management’s confidence in the company’s long-term growth prospects.
Analysts remain bullish on Nvidia, citing its leadership across GPUs, networking, systems, and CUDA software, alongside strong AI demand from hyperscalers and enterprises. Expectations for sustained growth are also supported by ongoing supply constraints in advanced AI hardware.
Recent reports suggest SpaceX is exploring a roughly $40 billion financing package to purchase Nvidia chips, underscoring the scale of AI infrastructure demand.
Despite the bullish outlook, investors continue to monitor risks including rising memory costs, margin pressure, competition from AMD and custom AI chips, and the possibility of slower AI spending growth as customers seek greater returns on their investments.
Featured image via Shutterstock