JPMorgan reiterated its “Overweight” rating on Apple (NASDAQ: AAPL) on October 19 and kept its $360 Apple stock price target, both due to positive demand trends across the iPhone lineup.
In the note, the bank specifically highlighted strong early demand for Apple’s new foldable iPhone Duo, with pre-orders opening on Friday and selling out virtually immediately, pushing delivery estimates into next year.
However, while current delivery timelines suggest demand may already exceed the revised shipment forecast, JPMorgan cautioned that it remains too early to draw definitive conclusions about the foldable iPhone’s long-term performance.
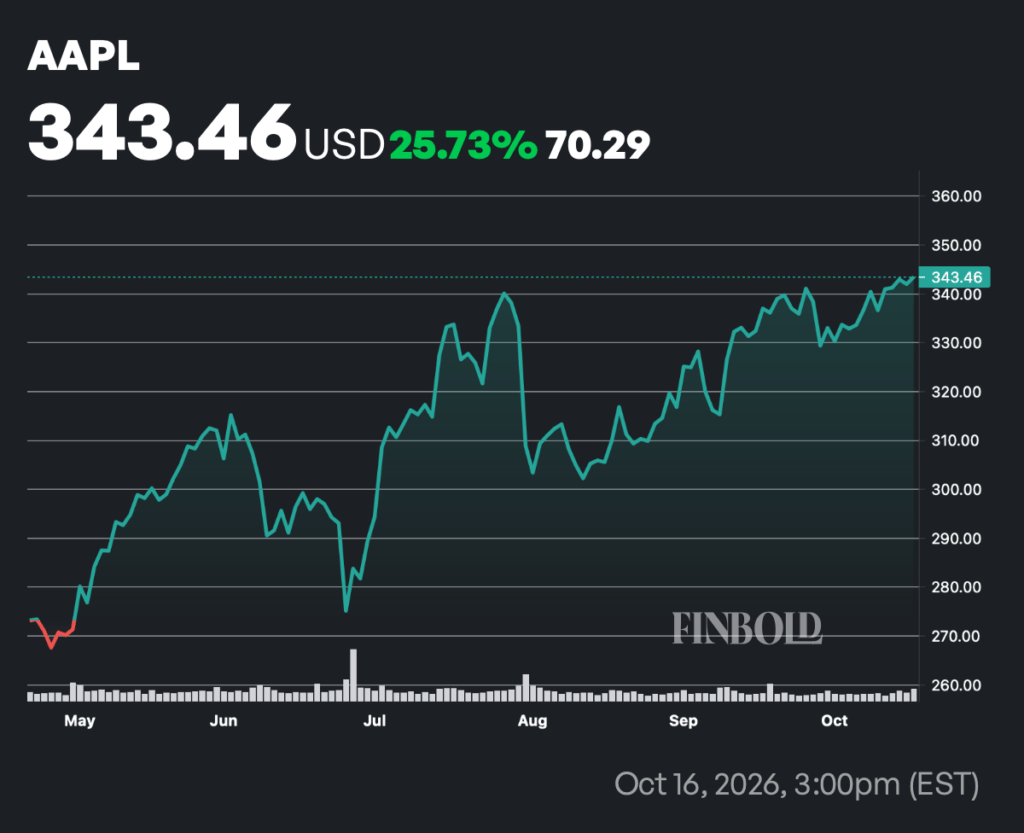
Apple shares last $343.46, after gaining approximately 27% over the past six months, meaning JPMorgan’s forecast implies roughly 5% upside from the current levels.
iPhone demand is constructive, JPMorgan says
After some recent iPhone Pro demand concerns in China, delivery estimates have largely normalized over the past week. Notably, lead times for the lineup now remain unchanged in the U.S., Germany, and the United Kingdom.
JPMorgan believes the situation supports its constructive outlook for the iPhone 18 cycle in fiscal 2027. That is, the firm expects demand volumes to remain resilient, with revenue growth benefiting from pricing changes and a varied product mix.
However, Jefferies maintained its “Sell” rating on Apple on October 19 as well, with a price target of $263, which implies a downside of 23% from the last closing price. The bearish take focused primarily on the fact that the latest iPhone generation is experiencing an increasingly weak launch in China.
Wall Street divided on Apple stock price targets
Recent analyst calls also highlight some different perspectives on Apple’s demand outlook, profitability, and upcoming product cycle.
For example, UBS reiterated its “Neutral” rating on Apple on October 16, citing concerns about iPhone demand and noting that Pro model delivery times were shorter than at the same point last year.
On the same day, Evercore ISI maintained an “Outperform” rating, highlighting changes in iPhone 18 delivery estimates, including, again, reductions in lead times in China.
Overall, Wall Street sees a modest 2.5% downside potential for the iPhone maker over the next 12 months, with the average AAPL share price target of $334, judging by the analyst data collected by TipRanks over the past three months.
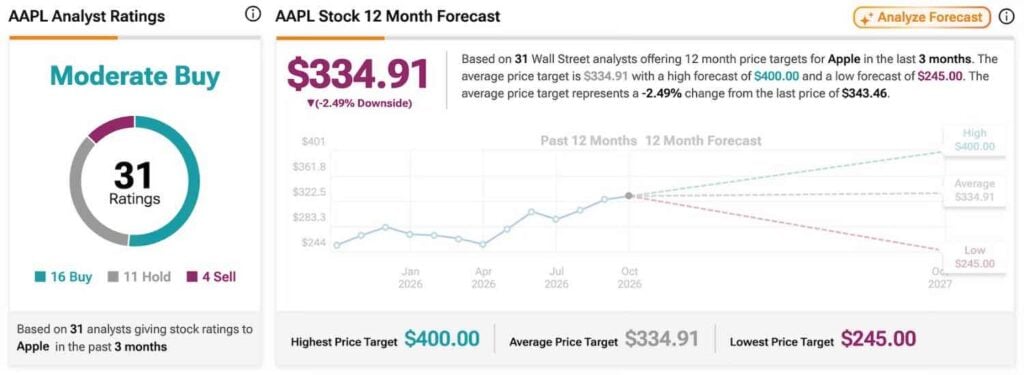
The consensus is the combined result of 31 analyst ratings in the aforementioned time period, with 16 of them being “Buys,” 11 “Holds,” and four “Sells.”
Featured image via Shutterstock