Micron Technology (NASDAQ: MU) could plunge to $400 in early June 2027 if its current rally repeats a price pattern from the Dot-com bubble.
The target implies a 61.1% decline from Micron’s last closing price of $1,029.
According to analysis by TradingShot outlined in a TradingView post on October 9, the correction could precede another rally that extends the artificial intelligence (AI) bull cycle toward 2030.
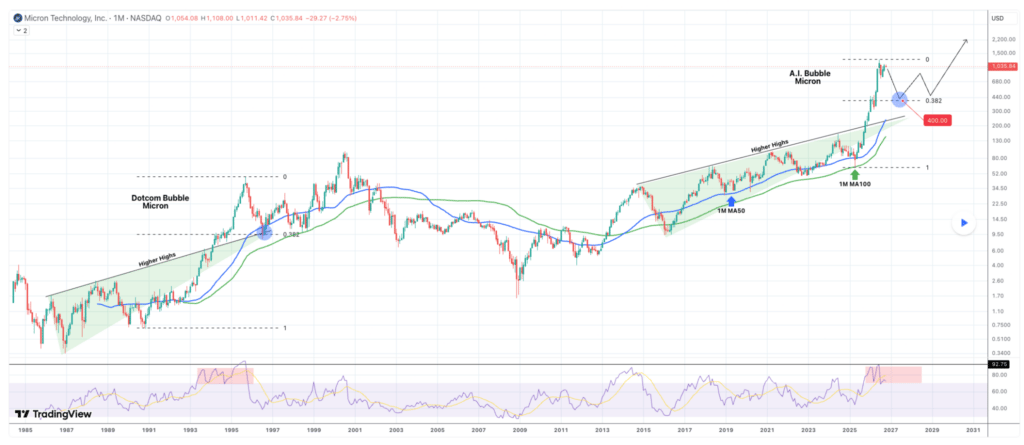
The analysis compared Micron’s current AI-driven rally with its advance in the 1990s. Both periods feature a long-term trendline of higher highs, followed by an upward breakout and a parabolic rally.
After peaking in September 1995, Micron corrected sharply toward its monthly 50-period moving average (MA), bottoming near the 0.382 Fibonacci retracement level.
TradingShot suggested a similar pullback could take the stock to $400 before it resumes its upward trajectory.
MU stock momentum
The monthly relative strength index (RSI) also shows similarities between the two cycles. Micron’s RSI recently reached 92.75, compared with 97 at the September 1995 peak, indicating exceptionally strong momentum and potentially overbought conditions.
TradingShot also highlighted the monthly 100-period moving average, which supported Micron through much of its previous decade-long advance.
However, the historical comparison does not guarantee a repeat, and the projected June 2027 low remains a technical scenario.
Meanwhile, Micron’s fundamentals remain strong. Fiscal Q4 2026 revenue reached a record $54.23 billion, up 31% quarter over quarter and 379% year over year. Non-GAAP earnings per share of $33.42 beat estimates of $31.6, while non-GAAP gross margin reached 87%.
DRAM revenue hit a record $39.8 billion, while NAND generated $14.1 billion. The core Data Center Business Unit brought in $18 billion, up 56% sequentially, driven by AI demand for high-bandwidth memory (HBM), DRAM and data center storage.
For fiscal 2026, revenue surged 256% to $133.19 billion, while non-GAAP net income reached $86.76 billion, or $75.52 per share.
For Q1 fiscal 2027, Micron forecasts revenue of $61.5 billion, plus or minus $1.5 billion, non-GAAP EPS of $38.15, plus or minus $1.00, and a gross margin of approximately 86.25%.
Micron stock fundamentals
The outlook is supported by tight memory supply and sustained AI demand. More than 75% of fiscal 2027 shipments were already committed, customers were discussing 2028 allocations, and much of next year’s HBM output had been sold at higher prices.
Additionally, Micron has signed 26 multiyear strategic customer agreements, some extending into 2030–2031, while ramping HBM4 production and expanding manufacturing capacity.
However, the technology company still faces risks, including industry cyclicality, rising capacity, slower AI spending, and customer concentration.
The company recently settled a patent dispute with Netlist for $600 million, including a five-year license, while a Taiwan workers’ union authorized a strike over bonuses.
Following its sharp rally, Micron is also vulnerable to profit-taking and valuation concerns.
Featured image via Shutterstock