Fintech dealmaking has picked up pace in 2026. Global fintech investment reached $103.1 billion in the first half of the year, up from $72.2 billion in the previous six months, and M&A made up the largest share: $67.9 billion across 394 deals. Fewer deals are carrying more money, as investors concentrate capital on companies with proven business models, and AI-focused fintechs alone drew $21.4 billion. With buyers paying for scale and capabilities, the open question is what a regulated financial business is really worth.
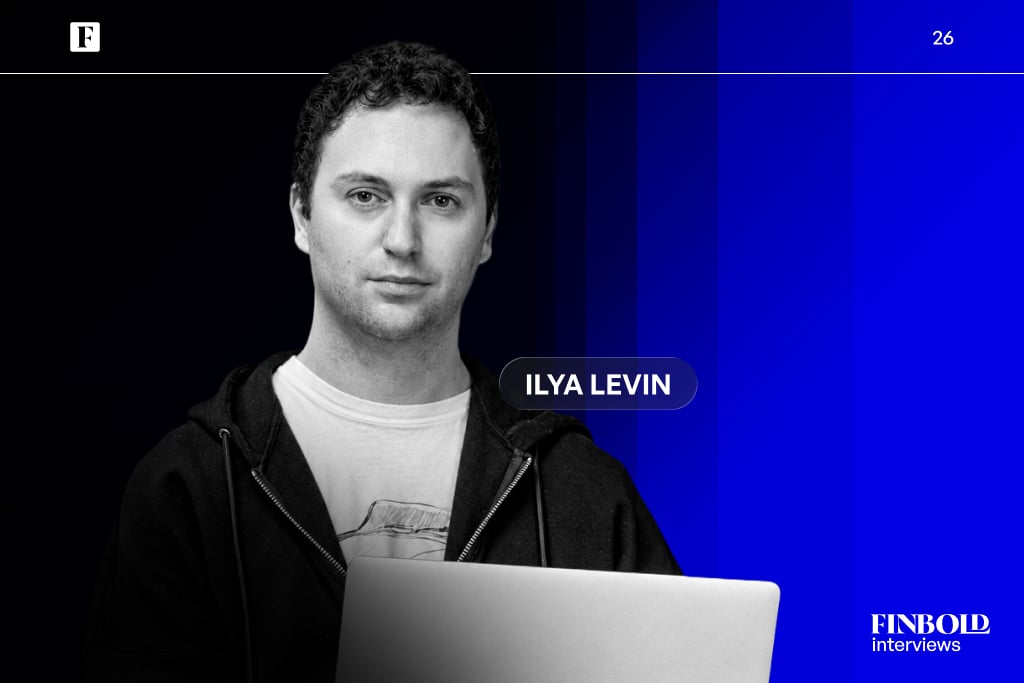
Ilya Levin spent more than a decade on Sberbank’s in-house M&A and corporate development team, rising to managing director, and later advised a group of investors on acquiring control of a US digital banking startup. He now leads deals execution on the private equity team of a Central European Investment Group. A mathematics and economics graduate and CFA charterholder, he is a member of the 2026 Expert Council of the NextWave Awards, where he evaluated the Fintech Revolution and Sustainable Business Model nominations. In this interview, he talks about why fintech valuations go wrong and how deal terms should handle regulatory risk.
As a Fintech Revolution judge, how do you assess different businesses?
I approach an application the way I approach an investment case, starting with where the revenue comes from, not how large the market is. If winning a customer costs more than the customer brings, growth only increases the loss, so I check unit economics. Then I check dependencies: whose license the business runs on, and whether revenue relies on one partner bank, payment network or client. Growth in users is interesting, but growth in revenue per user is convincing.
Buyers often price a licensed fintech like a software firm. Is that a mistake?
Yes. A software multiple ignores two things: the capital a regulated business must hold and cannot freely distribute, and the regulator, who becomes a third party to the deal and can delay or block it. A license is an asset because it can save years of market entry. It is also a liability, with capital requirements, compliance costs and supervisory approval of the new owner. In some markets approval is predictable; in others, the timing and outcome are hard to plan, and that uncertainty has a price.
How does a large financial group decide whether to buy a capability, build it or partner for it?
The central question is time: how long would building take, and what does the delay cost compared with the premium for buying? Buying fits what takes years to create, such as a license, a customer base or a team with rare skills. Building fits capabilities close to what the group already does. There is also a third option, a partnership, including a white-label arrangement where the company offers a partner’s product under its own brand. For a large financial institution it rarely works as a permanent solution, because the company ends up depending on someone else’s technology for something its customers see as its own. It is, however, a faster way to reach the market than building, and it can serve as an interim step before an acquisition: the company tests demand and gets to know the partner from the inside before deciding whether to buy it. The hidden cost of buying is integration, because a small digital company inside a large bank can lose the agility it was bought for.
How do regulatory differences between jurisdictions change the way a deal is structured or priced?
The parties can agree on a price and sign, but they cannot close until the regulators approve. The less predictable that period, the more the SPA must cover: a long-stop date after which either side can walk away, who bears the cost if approval is refused, the level of effort the buyer must undertake to obtain approval, walk-away rights if the regulators’ requirements are too harsh, break-up fees if approval is not granted, how the business is run between signing and closing, and what price adjustments apply if the period between signing and closing is long.
How does evaluating a young fintech differ from evaluating an established bank?
An established bank has years of reported results and a balance sheet to study. A young fintech has little history, so the analysis shifts to dependencies: the partner bank or other license holder, the payment networks it relies on, including card issuers if the product involves cards, the technology providers and the founders. The first check is who actually holds the customers’ money, since many fintechs have no license of their own or very limited ones and use partner banks either for all services or at least for deposit taking, and what happens if that partner leaves. The second is unit economics and retention rates: whether growth comes from a product people keep using or from paid acquisition that stops when marketing stops. For a thorough analysis, you also need to look at retention by customer cohorts, and at customer acquisition cost versus its payback period and the lifetime value of a client.
How do you decide how much of the AI premium to pay, and when do earnouts or deferred payments help?
The AI premium is a bet on future results. I would pay at closing for what the technology does today, such as lower costs or better fraud detection that shows in the numbers and could be verified in due diligence, and tie the rest to results. An earnout does that: part of the price is paid only if agreed targets are met. A non-contingent deferred payment is paid on a set date regardless of results, so it does not help much here. However, an earnout works only if the metric is defined precisely, can be measured simply and, in case of a dispute, verified by an independent expert, and cannot be easily distorted by either party.
You have compared a good term sheet to code. What does that mean in a fintech deal?
The point is valid for any M&A deal, not only for fintech. A good algorithm must work correctly for every set of inputs, not only for likely ones, and a contract is the same. The parties’ behavior should be defined properly for any potential outcome. The most dangerous cases are the ones nobody discussed. My first degree is in mathematics, and it shaped how I write documents. However, in fintech this matters even more, because regulation and technology change during the life of a deal. A license condition can shift, a partner bank can exit, a key system can need replacing. Each is a “what if” that needs an answer on who bears the cost and who decides.
Where will fintech consolidation go next?
Large financial groups will continue buying capabilities they can’t build quickly enough, especially in AI, fraud prevention and compliance. Consumer apps with a user base but no profit will be sold cheaply: in such deals buyers usually want the license, if there is one, the customer base, the technology or the team, so the business is not valued as a going concern at high multiples.
Read more interviews here.