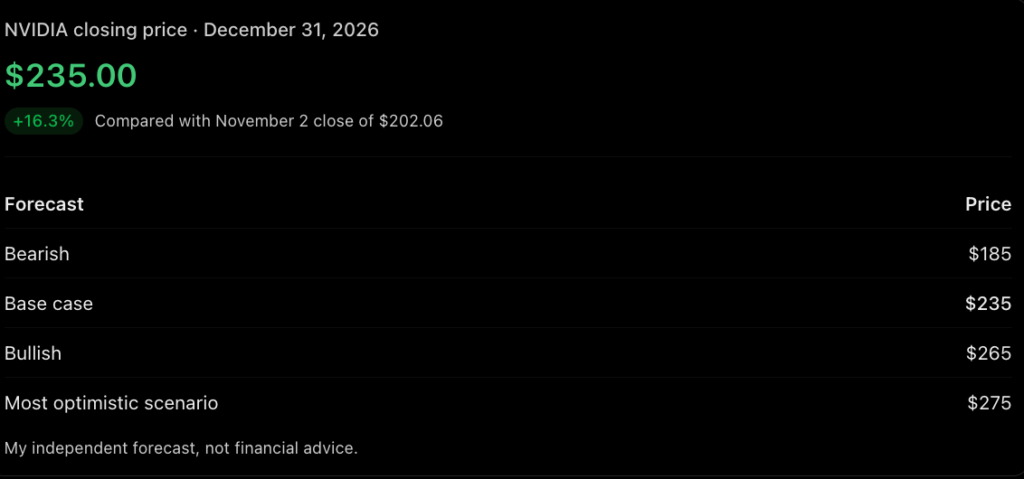
Nvidia (NASDAQ: NVDA) stock could recover towards $235 by December 31, 2026, according to a forecast by ChatGPT, which anticipates a rebound following the semiconductor giant’s recent share-price correction.
The prediction represents an upside of approximately 16% from Nvidia’s November 2 closing price of $202.
ChatGPT’s forecast placed Nvidia’s year-end price within a base-case range of $225 to $245, although the stock could fall towards $185 if concerns about AI infrastructure spending intensify.
Advertisement
In a more optimistic scenario, shares could climb to $265, with $275 representing a more bullish outcome.
Nvidia stock price struggles
The forecast comes as Nvidia shares struggle to recover from their October decline, which saw the stock retreat from a record closing high of $239 to $204 at the end of the month.
Despite the correction, Nvidia remains above its 52-week low of $164, while trading considerably below its 52-week high of $243.
At the same time, Nvidia’s technical outlook remains a challenge to the bullish forecast, with shares falling below their 50-day and 200-day moving averages (MA).
The $198–$199 range represents immediate support, with a break potentially exposing shares to $189–$191 or even $185. On the upside, Nvidia faces initial resistance at $216–$221, followed by $226–$227.
The weakness comes amid broader concerns about AI infrastructure spending and whether major technology companies can sustain their capital expenditure while generating sufficient returns.
Advertisement
NVDA stock fundamentals
Nvidia’s continued revenue growth, particularly in its Data Center business, is a key factor supporting the $235 forecast.
In its second-quarter fiscal 2027 results released on August 26, the company reported revenue of $96.2 billion, up 106% year over year.
Data Center revenue surged 117% to $89 billion, accounting for approximately 92.5% of total revenue. Non-GAAP diluted earnings per share rose 120% to $2.22, while gross margin stood at 75%.
For the third quarter, Nvidia projected revenue of $108 billion, plus or minus 2%, and a non-GAAP gross margin of approximately 74%.
The guidance signals continued demand for its AI processors despite concerns about infrastructure spending and excludes Data Center compute revenue from China.
Further growth could come from wider adoption of its Blackwell and Vera Rubin platforms, alongside investments in AI infrastructure, robotics, physical AI and automotive applications.
Advertisement
Nvidia’s upcoming earnings
Nvidia’s November 17 earnings report is another key catalyst. In this case, analysts expect third-quarter fiscal 2027 revenue of approximately $109 billion and adjusted EPS of $2.47, slightly above the company’s revenue guidance.
Investors will watch Data Center growth, Blackwell demand, gross margins, and forward guidance to determine whether shares can recover towards ChatGPT’s $235 target.
Nvidia’s ability to sustain growth despite China export restrictions will also remain important, particularly after the company disclosed that permitted H200 shipments to selected Chinese customers represented less than 1% of Data Center revenue.
Featured image via Shutterstock