JPMorgan lowered its Apple (NASDAQ: AAPL) stock price target from $360 to $355 on Tuesday, November 3, maintaining an “Overweight” rating.
With Apple shares up 25% in 2026, the bank remains positive on the company’s long-term prospects, particularly as a stronger hardware product cycle could support growth in the installed base.
Furthermore, JPMorgan raised its Apple product revenue forecasts for fiscal 2027, with most of the upward revisions coming from Mac and iPad sales and stronger iPhone pricing.
Advertisement
However, the research note also moderated the outlook for Services revenue growth and gross margins, pointing to challenging product and services margin dynamics.
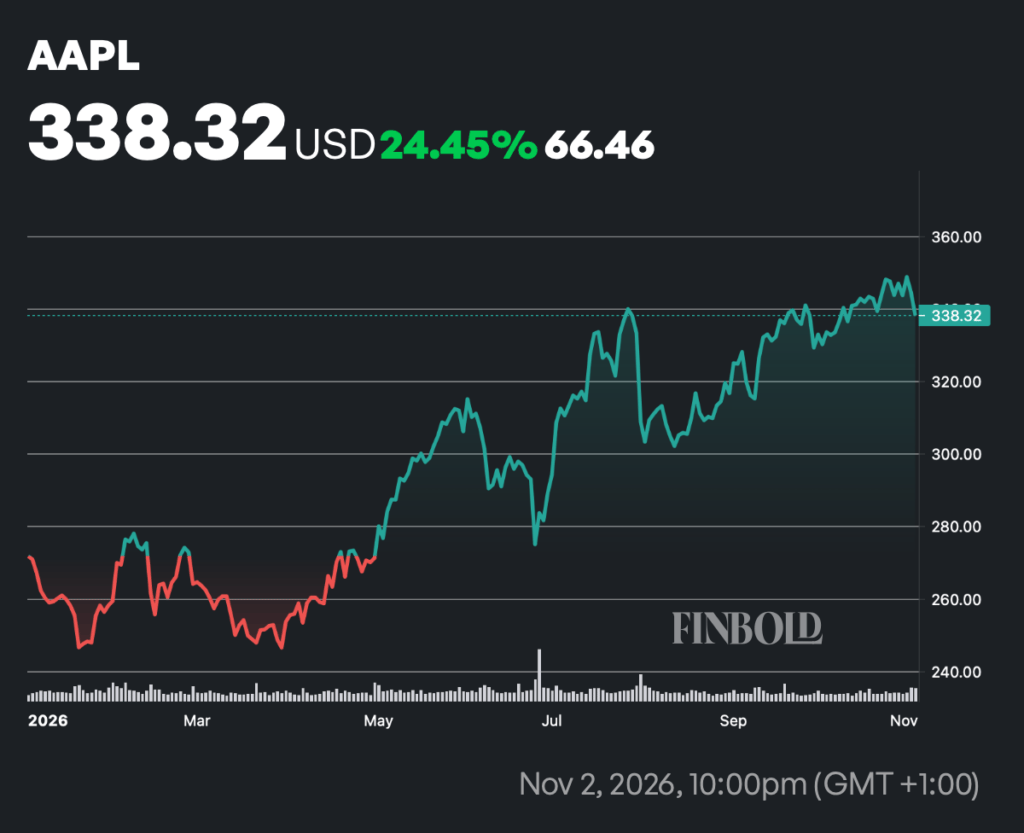
Apple stock to benefit from a strong hardware cycle, but Services business is lagging
Discussing the stock further, JPMorgan noted that Apple’s product and iPhone revenue both met expectations despite market concerns surrounding supply constraints and consumer sensitivity to more aggressive pricing.
Moreover, the bank expects processor-related supply constraints to become more relaxed into the first quarter, while production of Apple’s Duo product is also improving. However, the analysis cautioned that it is still not clear when supply will be sufficient to meet demand.
Services, on the other hand, present a more complicated picture. JPMorgan highlighted several headwinds, including weakness in mobile gaming, changes to the App Store business model, and challenges involving third-party licensing.
Nevertheless, the firm sees potential for Apple’s stronger hardware cycle to expand its installed base and eventually support a recovery in Services growth. Explaining why, the bank noted that a broader range of offerings and geographic expansion could help management capitalize on the growing ecosystem.
Morgan Stanley agrees on Services growth, cuts Apple share target
Morgan Stanley also lowered its price target on Apple from $355 to $350 while maintaining an “Overweight” rating, pointing to strong product demand and pricing power but raising concerns about slowing Services growth.
Advertisement
As Morgan Stanley notes, the Services business remains a source of concern, and management attributed the slowdown to weaker App Store performance, third-party licensing developments, and unfavorable foreign exchange movements.
Morgan Stanley said the deceleration raises additional questions about the potential impact of artificial intelligence on key parts of Apple’s Services business, as AI-driven changes could disrupt existing business models and revenue streams.
Reflecting the situation, the firm reduced its fiscal 2027 earnings-per-share (EPS) estimate by $0.05 and its calendar 2027 forecast by $0.16, bringing them to $9.85 and $10, respectively.
Featured image via Shutterstock