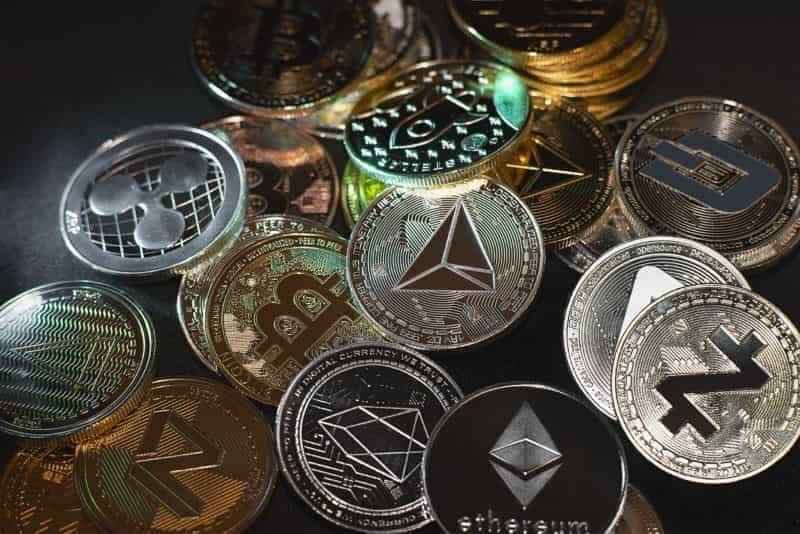
Picture two people who’ve never met. One has stablecoins sitting idle in a wallet, earning nothing. The other holds Bitcoin they’re not ready to part with, but they’d like some spendable cash. Each has what the other wants.
Crypto lending is what connects them. One side supplies funds and earns interest, the other posts crypto as collateral and borrows against it. The mechanics are borrowed from traditional finance, with some important differences, so here’s how it works.
Fundamentals of Crypto Lending
So what is crypto lending in practice? It is the crypto-native version of a traditional loan or credit line. Depending on the product, a loan can run for a fixed term or stay open indefinitely, as long as the lender’s collateral requirements are met.
Who Borrows and Who Lends
So how does crypto lending work for each side of the market? On the borrowing side are crypto holders who would rather keep their coins than sell them. Credit scores do not matter, since the loan is secured by collateral, so these products are more accessible than traditional lending. You still need an account with a crypto app and enough collateral to qualify.
On the lending side are users and institutions that supply crypto or stablecoins and earn interest, which is paid by borrowers. How this works varies by platform. Some lend from their own balance sheet, while others pool funds from depositors.
Where You Can Borrow Against Crypto
Many popular crypto apps offer loans, both specialized lenders and all-in-one platforms. Multi-collateral credit lines are one of the more flexible formats around. Clapp offers them, and its rates can drop to 0% in the lowest LTV band.
How Does A Crypto Loan Work?
Suppose you hold Bitcoin or Ethereum and need euros or dollars. You deposit your coins as collateral in a crypto app and the fiat lands in your account. When you repay, you get your coins back.
How much you can borrow depends on the lender, but crypto loans are over-collateralized. That means you borrow a percentage of what your collateral is worth. If you deposit $50,000 in Bitcoin, you might be able to borrow around 70% of that, depending on the platform’s maximum loan-to-value (LTV) ratio.
LTV is the key number in any crypto lending product. It compares what you’ve borrowed with the value of the crypto you’ve pledged. Borrowing $20,000 against $40,000 in BTC puts you at a 50% LTV, while borrowing $10,000 against the same collateral puts you at 25%.
Crypto Lending Rates
On many platforms, the less you borrow relative to your collateral, the lower your interest rate. Lenders use LTV bands tied to different APRs to set what you pay, which rewards responsible borrowing and gives the platform a bigger buffer against market swings.
Rates also differ by platform, asset and loan type, so it pays to compare before you borrow. As your collateral’s value changes, you can move between LTV bands, which means your APR may not stay fixed.
Risks of Crypto Loans
The biggest risk is liquidation. It happens when your collateral’s value falls below the lender’s liquidation threshold, which is disclosed upfront. In a sharp market drop, borrowers need to top up their collateral or repay part of the loan to keep their coins. Otherwise, the lender may sell some or all of the collateral to cover the debt, depending on how far prices fall.
There is also platform risk. Whoever holds your collateral becomes a counterparty, so check how the lender stores assets and how transparent it is about its security practices before you commit. Look into its custody provider, asset protection measures, and safeguards beyond basic two-factor authentication.
Crypto Lending Works Best as a Bridge
If you need cash for a while and want to keep your coins, a loan can bridge the gap without a sale. A fixed-term loan fits a defined need, such as a one-off expense, since the amount, term and rate are set from the start.
A credit line suits less predictable needs. It has no fixed end date or repayment schedule, interest is charged only on the amount drawn, and the line stays open as long as the collateral holds up. That makes it a handy standby source of cash, especially in the multi-collateral form, where the pledged assets can be adjusted along the way.
Either way, the basics stay the same: borrow well below the maximum and read the liquidation terms before signing up. A low LTV is a borrower’s best cushion.
Featured image via Shutterstock.