Wells Fargo has raised its price target on Alphabet (NASDAQ: GOOGL), the parent company of Google, to $417 from $411.
In an investor note on October 6, the firm maintained its ‘Overweight’ rating, with the new target implying upside of about 20% from Alphabet’s current share price of $346.47.
According to Wells Fargo analyst Ken Gawrelski, external TPU sales are expected to become a significant growth driver for Google Cloud.
The firm projects Alphabet’s 2027 revenue will come in 14% above Wall Street estimates, primarily due to TPU-related sales. Wells Fargo also forecasts 2028 revenue and earnings per share to exceed consensus expectations by 20% and 5%, respectively.
The analyst expects the technology giant to generate approximately $9.2 billion and $11.5 billion in external TPU sales during the third and fourth quarters of 2026. Those sales are projected to boost Google Cloud Platform revenue well above current market expectations.
Wells Fargo subsequently raised its earnings-per-share estimates for 2026 and 2027 to $20.66 and $15.17, respectively, while increasing its 2027 revenue forecast by 4%. The firm’s valuation remains based on a 27.5-times multiple of its projected 2027 earnings.
The bullish view aligns with comments from Alphabet management highlighting growing demand for TPU systems from external customers in addition to their internal use across Google’s cloud infrastructure.
The price target increase comes as Google Cloud continues to benefit from growing AI demand. Alphabet recently reported 82% year-over-year cloud revenue growth and began generating revenue from external TPU sales.
Wells Fargo expects further cloud acceleration, supported by strong AI workloads, while search engagement remains healthy, with global search sessions up about 36% year-over-year. The firm also sees Google’s Gemini 4 Argon model strengthening the company’s position in the AI race.
Google stock risks
Despite the optimistic outlook, Wells Fargo highlighted several risks that could affect Alphabet’s future performance.
The firm pointed to increasing competition in search, questions surrounding the economics of TPU commercialization, and rising capital expenditures tied to AI infrastructure expansion.
Analysts are also monitoring whether Google can maintain its rapid cloud growth while balancing the substantial investments required to build new data centers and AI capacity.
Even so, broader Wall Street sentiment remains favorable. According to analyst consensus data by TradingView, Alphabet continues to carry a ‘Strong Buy’ rating, with the average one-year price target standing at $426.26, representing nearly 24% upside from current levels.
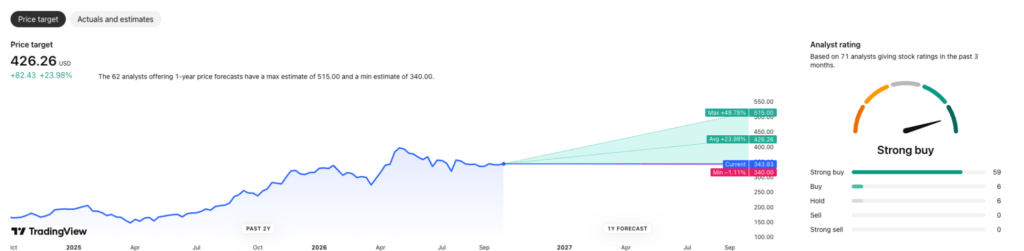
The highest target among analysts currently sits at $515.
Featured image via Shutterstock